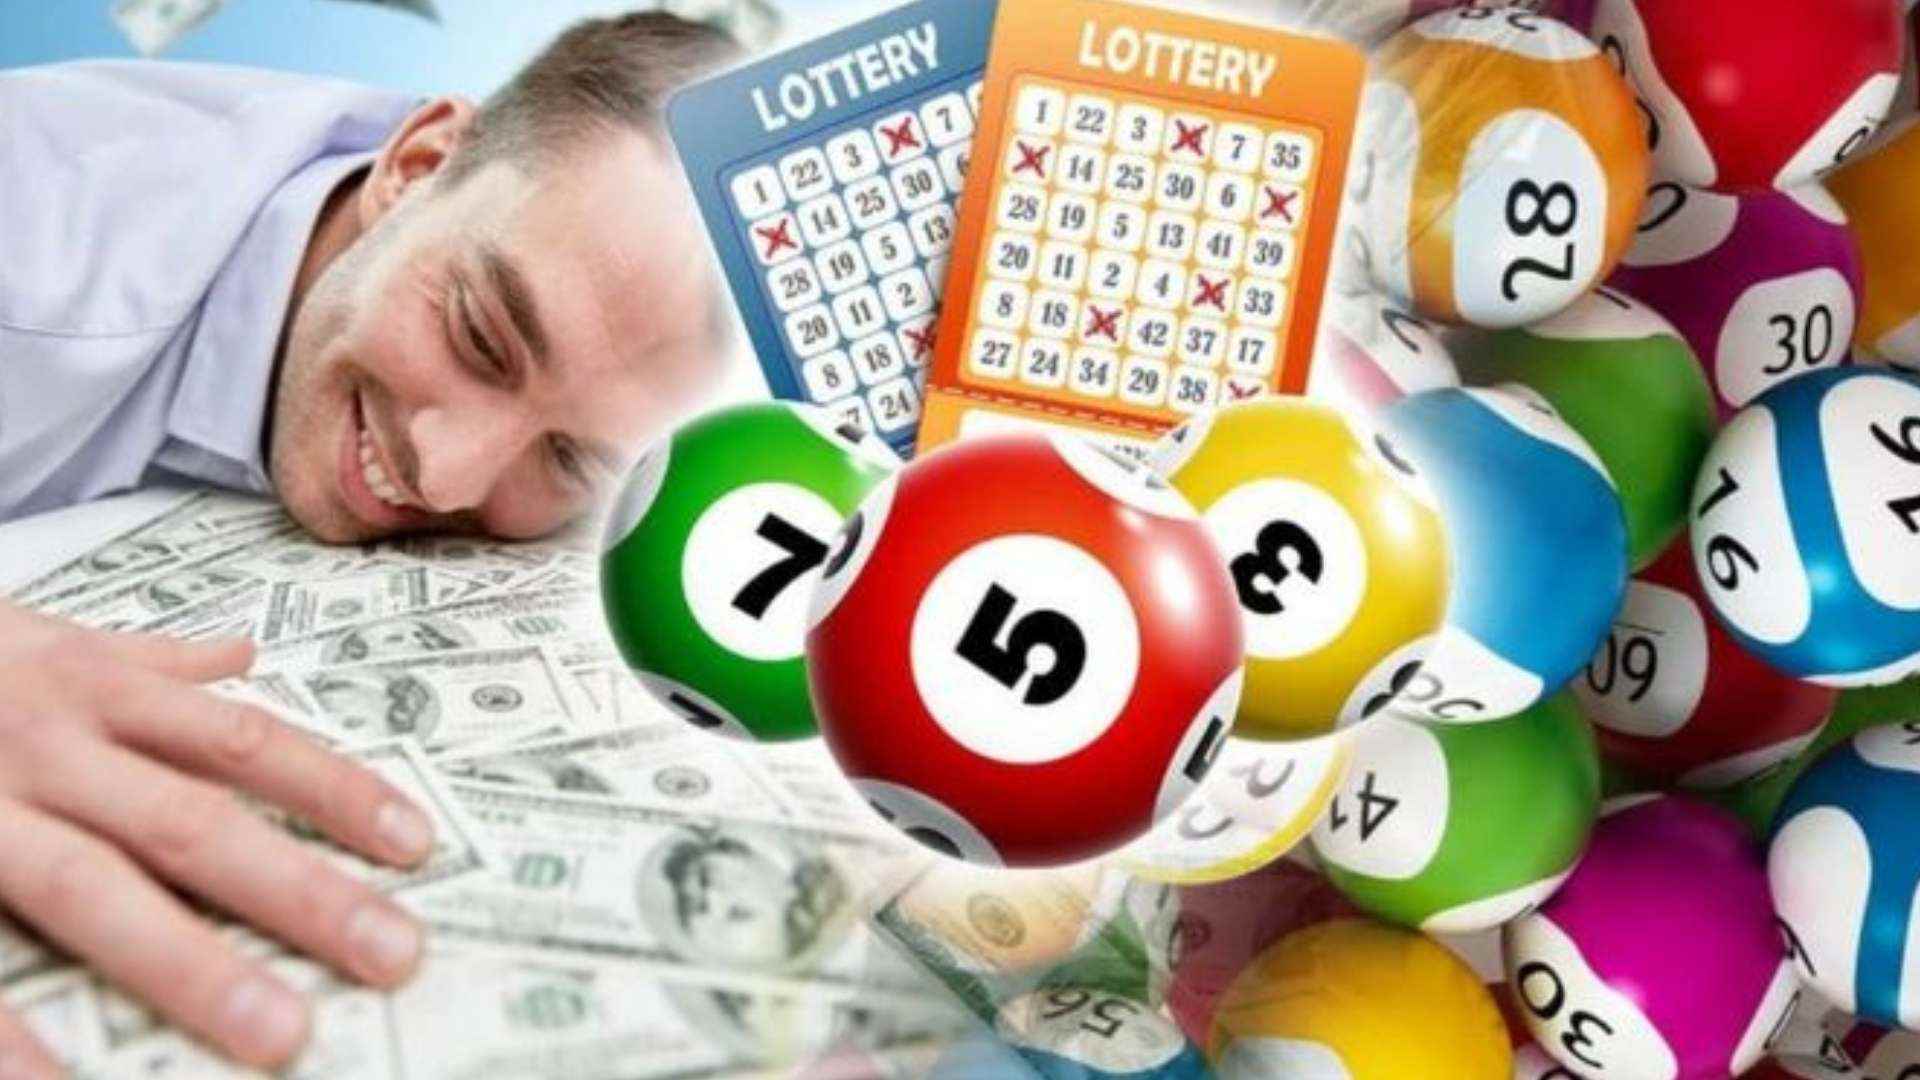
Winning a major lottery prize is a life-changing event that brings immediate excitement alongside significant financial responsibilities. While the thought of sudden wealth is thrilling, navigating the post-win period without a clear plan can lead to critical missteps. Taking calculated steps early on protects your new fortune and ensures long-term financial security.
Secure Your Winning Ticket and Maintain Anonymity
The first action every lottery winner should take is to sign the back of the winning ticket to establish official ownership. After securing the physical document in a safe deposit box, it is essential to keep the news quiet to protect your privacy. Limiting publicity prevents unwanted attention and reduces the pressure from unsolicited financial demands.
Depending on local regulations, you may have the option to claim your prize through a legal entity or trust to preserve your identity. Keeping your personal details private gives you the necessary room to make clear decisions without outside influence. Remaining discreet during the initial phase lays a solid foundation for your future wealth management.
Assemble a Professional Advisory Team
Before stepping forward to claim your jackpot, building an experienced team of professionals is a non-negotiable step. A certified financial planner, a tax accountant, and an estate planning attorney will help you navigate complex legal and tax obligations. Their expert advice ensures that every decision aligns with your long-term wealth goals.
Professional guidance helps prevent common financial traps that often catch new millionaires off guard. While waiting for your financial strategy to take shape, some individuals explore leisure options like the m88 apk for casual mobile entertainment. However, major life decisions regarding your windfall should always be directed by certified advisors.
Choose Between Lump Sum and Annuity Payments
Lottery winners face a major decision when selecting how to receive their prize money. Choosing a single lump-sum cash payout provides immediate access to capital, but it also results in higher upfront tax deductions. Alternatively, receiving annual payments through an annuity offers a steady income stream over several decades.
Evaluating which payout structure suits your lifestyle requires comparing long-term investment strategies against tax implications. An annuity provides financial safety by preventing overspending, while a lump sum offers investment flexibility under proper management. Consulting with your tax professional will clarify which option best serves your financial vision.
Create a Long-Term Budget and Gift Management Strategy
Managing sudden wealth requires establishing strict spending boundaries to protect your capital from depleting prematurely. Creating a comprehensive budget allows you to enjoy lifestyle upgrades while preserving the core principal of your payout. Setting clear limits on major purchases ensures that your wealth lasts for generations.
Developing a structured gifting policy is equally vital when handling requests from friends, relatives, or charitable causes. Establishing formal channels for donations prevents personal relationships from becoming strained over money matters. A well-planned financial roadmap allows you to share your fortune responsibly without compromising your financial peace of mind.